Joel Forbess and his team at Kimberly Clark Credit Union kept seeing the same thing. A member would take out a payday loan, then take out another one two weeks later to cover the first. The fee sounds small, about $15 for every $100, but over a year it works out to close to 400 percent. The whole balance comes due on the next payday, so plenty of people pay the fee, borrow again, and never get the balance down.
KCCU didn't want another product flyer. They wanted something their staff could share with a member in that spot: a plain explanation of what's happening and a clear way out. They asked us for it.
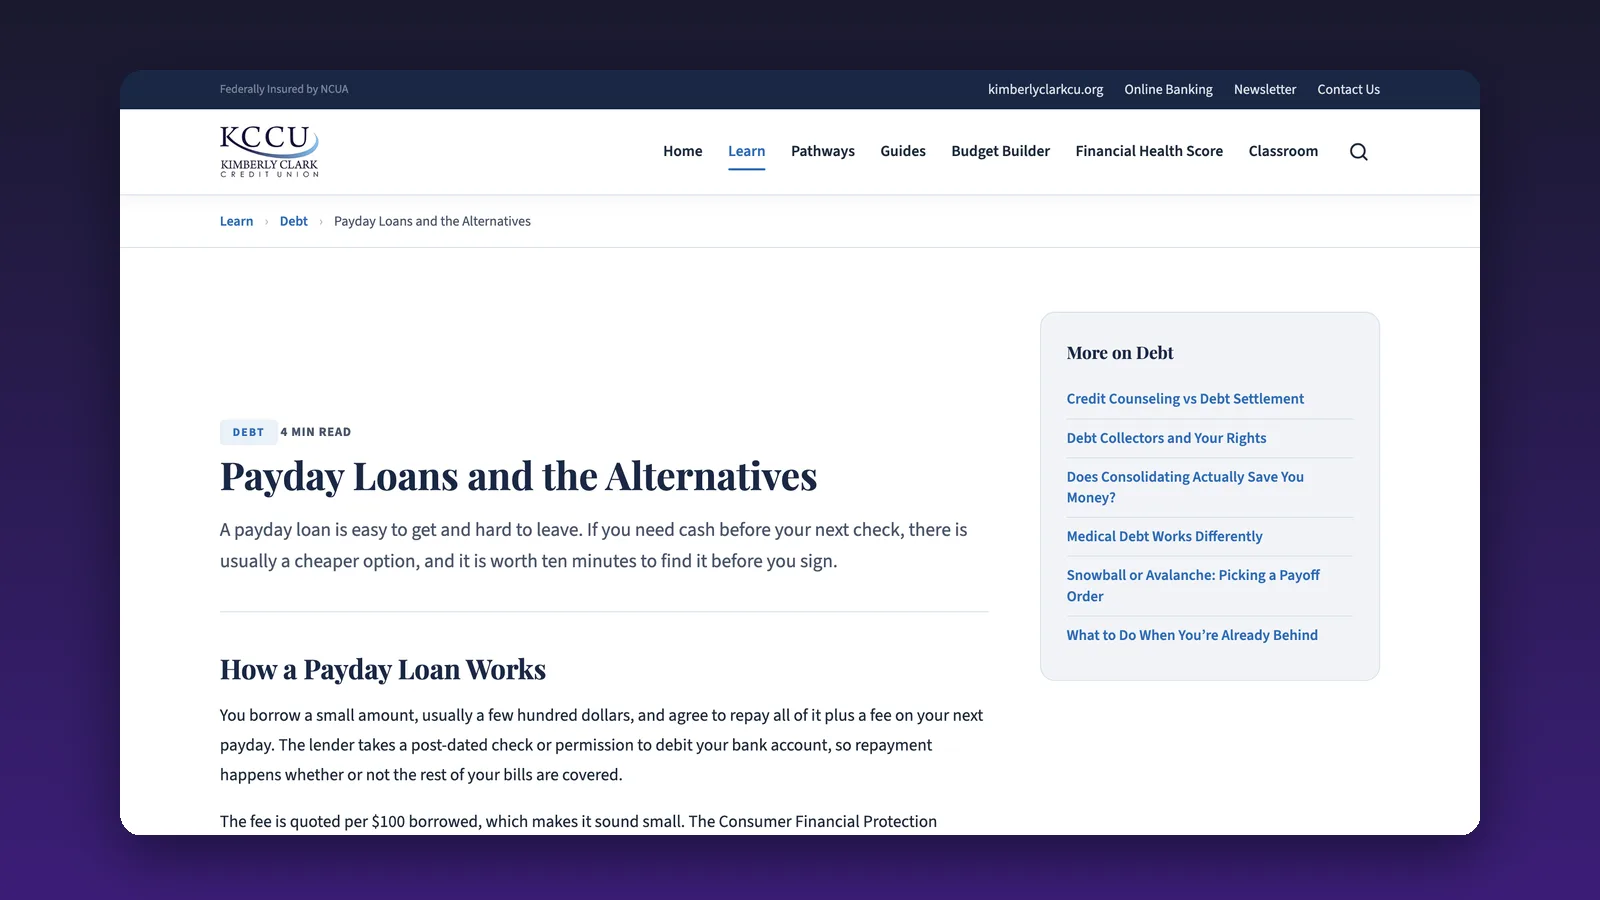
We researched it, wrote it, and put it on KCCU's financial wellness site as Payday Loans and the Alternatives. It's written for someone who already has a payday loan or is about to take one, and it treats them like an adult. It explains how the loan works, why it's so hard to leave, and what to do next.
KCCU now has a single link to share, and it doesn't stop at reading. A member can open the Budget Builder and see where the next paycheck is going, read what to do when they're already behind, or go straight to KCCU's consumer loans. An installment loan from their own credit union usually costs far less than rolling over a payday loan, and the page says so under KCCU's name.
Then we added it to every financial wellness site we run. One credit union asked, and every credit union we work with got it at no extra cost.
The people most likely to need a payday loan are the people who can least afford one. A credit union is usually the cheaper answer. Members just need to know to ask.